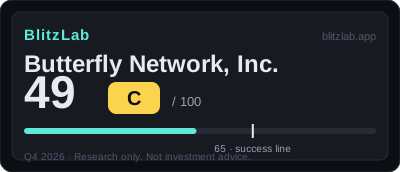
Butterfly Network, Inc. — Blitz Index 49 (C)
Butterfly Network scores 49 — handheld ultrasound growing 52% with software at half of revenue, held back by a founder who controls 71% of the votes and a cash runway of about 2.8 years.
Last re-scored: October 29, 2026.
Confidence: Medium · Category: frontier
Score breakdown
| Section | Score | Detail |
|---|---|---|
| A · Speed | 18 / 25 | Q3 revenue $32.6M (+52% YoY, US +71%, software +145%), nine months +39%, FY2026 guidance raised to $123–126M (+26–29%) — a turnaround from 2025's stall |
| B · Moat | 29 / 60 | Handheld ultrasound plus a software subscription layer (B4 8, adjusted gross margin 73.0%) — but distribution is direct sales and the installed base is still small |
| C · Creative destruction | 11 / 15 | Handheld point-of-care ultrasound displacing cart-based imaging and specialist-only scanning — a real displacement, now extending into embedded licensing |
| D · BlitzFailing | −9 | Founder holds 71% of votes via Class B shares at 20 votes each (D3 −3); cash burn of $32.4M in nine months (D1 −2); a 2025 inventory writedown (D2 −2); three lawsuits pending (D4 −2) |
Think we scored it wrong? Score it yourself →
Radar axes (0–100): Moat 48.3 · Speed 72.0 · Creative 73.3.
Watch item
Gates: G1 ✓ (confirmed — growth re-accelerating: Q3 +52%, software +145%, guidance raised) · G2 ✓ (estimated — point-of-care ultrasound extrapolates to ~$9.7B by 2036, ~7.9× the $1.23B bar). 16 points below the 65-point threshold — first score. No FLAG: deductions of 9. Watch: whether Q4 growth holds past the +3% guidance, whether embedded licensing becomes recurring high-margin revenue, and whether the cash runway forces a raise in 2027.
Strengths
- Growth accelerating: Q3 revenue of $32.6M (+52% YoY), nine months +39%, FY2026 guidance of $123–126M raised (+26–29%)
- Software shift: software and services are ~50% of revenue, Q3 +145% — recurring revenue rising as a share
- High margin: adjusted gross margin of 73.0% in Q3 (from 63.9%), TTM ~70.3%, adjusted EBITDA loss of just −$1.2M — near breakeven
- Second growth curve: embedded licensing (Midjourney co-development) plus FedRAMP certification opening the federal market
- No debt: long-term borrowings of $0, cash of $122.3M
Concerns
- Founder voting control of 71% (Class B at 20 votes a share) — shareholders effectively cannot check the founder (D3 −3)
- Cash burn: nine-month operating cash outflow of $32.4M and worsening, a runway of ~2.8 years — dilutive funding ahead (D1 −2)
- Q4 guidance of only +3% — the acceleration is not yet confirmed to last
- Inventory writedown precedent: a $17.4M writedown in Q3 2025 produced a quarterly gross loss (D2 −2)
- Three lawsuits in progress: a Rose class action plus two shareholder derivative suits, damages undetermined (D4 −2)
Research notes
Thesis: the turnaround is real — and so is the founder's grip
Butterfly Network enters the BlitzLab record with a first scoring of 49 out of 100, grade C, built from Speed 18 out of 25, Moat 29 out of 60, Creative Destruction 11 out of 15, and deductions of 9. The total sits 16 points below the 65-point line, and the shape of the score is the story: creative destruction converts to 73.3 and speed to 72.0, while the moat converts to only 48.3. This is the handheld-ultrasound company — trailing-twelve-month revenue of about $123.3 million — that stalled in 2025 (5% third-quarter growth, an inventory writedown) and has now turned: third-quarter revenue grew 52%, software grew 145% to about half of revenue, the adjusted gross margin reached 73.0%, and the adjusted EBITDA loss narrowed to $1.2 million, near breakeven. The counterweight is governance: the founder holds 71% of the votes through Class B shares carrying 20 votes each.
The gates: both pass — the runway is the question
Gate 1, two pieces of product-market-fit evidence for a growth company, passes on a confirmed basis. Revenue is re-accelerating — Q3 +52%, nine months +39% — and the second curve is showing in embedded licensing and a FedRAMP certification that opens the federal market. Gate 2, a ten-year market ceiling at least ten times current revenue, passes as an estimate: point-of-care ultrasound extrapolates to about $9.7 billion by 2036, roughly 7.9 times the bar of $1.23 billion. The fourth quarter of 2026 has not been reported at T, and its reporting date is unconfirmed — it is not a company-confirmed date and must not be presented as one — and no outcome is anticipated here. That is the balance of the record at T: a genuine turnaround with a high margin, a founder whose control no shareholder can check, and about 2.8 years of cash at the current burn — so the self-funding turn, not the growth rate, is the next test.
What the business is: a chip, a subscription and a licence
Butterfly Network puts ultrasound on a semiconductor chip. Its Ultrasound-on-Chip probe turns a phone or tablet into a handheld scanner, and the business earns in three ways: selling the probes, selling software and services on subscription through Butterfly Cloud and its AI tools, and licensing the chip platform to non-competing fields through Butterfly Embedded. The subscription leg is now about half the business: software and services were $17.0 million in the third quarter, up 145% year on year, and $45.7 million in the first nine months, up 120%. Distribution runs through direct sales, distributors and eCommerce across more than 30 countries, with enterprise and hospital-system contracts converting from the pipeline. The second curve is Embedded — joint development partnerships, including one with Midjourney, that license the platform rather than selling a device — and a FedRAMP certification that opens the federal government market. The first revenue from the Home & Community Care programme was expected in November 2026.
Why it scored 49: a turnaround with a 73% margin
Speed is 18 out of 25, converting to 72.0. Growth (A1, 8 of 10) is a re-acceleration after a stall: revenue went from $65.9 million in fiscal 2023 to $82.1 million in fiscal 2024 (up 24.5%) and $97.6 million in fiscal 2025 (up 19.0%), then $91.7 million in the first nine months of 2026 (up 38.8% year on year) and $32.6 million in the third quarter (up 51.7%), with US revenue up 71% and fiscal 2026 guidance raised to $123–126 million, up 26–29%. The caution is in the fourth-quarter guidance of $31–34 million, only about 3% above the prior year, so the acceleration is not yet proven to last. Capital speed (A2, 3 of 5) is pre-self-funding: a 2025 offering raised $81.0 million net and cash stands at $122.3 million, but operating cash flow was negative $32.4 million in nine months, worse than negative $21.7 million a year earlier, even as the adjusted EBITDA loss narrowed to $1.2 million in the quarter from $8.1 million — near breakeven on that measure. Hiring (A3, 3 of 5) shows about 220 employees at the end of January 2026, revenue per employee rising from $444,000 in fiscal 2025 to about $560,000 on a trailing basis, though operating expenses are still 115% of revenue. Share momentum (A4, 4 of 5) is the growth rate running at more than six times the point-of-care ultrasound market's roughly 8%. The moat is 29 out of 60 (48.3): network effects 6, distribution 7, market size 8 and gross margin 8, the last on a gross margin of 73.0% in the quarter — against negative 17.5% a year earlier, when a $17.4 million inventory writedown struck — and about 70.3% on a trailing basis. Creative destruction is 11 out of 15: the displacement of cart-based ultrasound by a pocket device (4), the irreversibility of bedside imaging workflows (4) and the lowering of health-system costs (3).
The risks: founder control, a 2.8-year runway and three lawsuits
The deductions total 9, spread across all four items. Governance (D3, minus 3) is the most structural: founder Jonathan Rothberg holds all of the Class B shares, carrying 20 votes each, and about 71% of the votes at the end of 2025, while Class A holders effectively have no vote; the 10-K itself warns that concentrated control may be exercised in ways adverse to shareholder interests. Debt (D1, minus 2) is not borrowing — long-term debt is zero and cash is $122.3 million — but burn: at the current pace of about $43 million a year, the runway is about 2.8 years, and the next funding would be dilutive equity, as the 2025 offering was. Revenue quality (D2, minus 2) carries the 2025 inventory writedown of $17.4 million, which turned a quarter's gross result negative, and the project-like character of Embedded revenue, which is not yet repeat subscription revenue. Regulation and litigation (D4, minus 2) is three live cases: the Rose class action from 2022 over SPAC-merger statements, with only a $0.3 million provision recognised in nine months and damages unspecified, plus two shareholder derivative suits, Koenig and Bhavsar. No regulatory investigation is currently under way, and the FedRAMP certification counts the other way.
What would change the score
The decisive test is self-funding: operating cash flow turning positive would remove the runway question and the dilution deduction at once, and the adjusted EBITDA loss of $1.2 million suggests it is close on an accounting basis — the gap is working capital. The second is Embedded becoming repeat licensing revenue rather than project revenue, which would also lift the margin story's durability. Growth must clear its own test: fourth-quarter revenue against guidance of only about 3% growth will show whether the 52% third quarter was a turn or a spike. Governance will not change quickly — the 71% vote is a structural feature — but litigation resolution would remove the overhang, and a clean inventory record over several quarters would retire the writedown precedent. International revenue, down 5% in the third quarter, is the distribution item to watch: the moat's distribution score of 7 assumes it recovers.
More Frontier companies
Other Frontier names on the Blitz Index, highest score first: Rocket Lab (62/B), Tesla (62/B), Illumina, Inc. (61/B).
Next earnings
Q4 2026 · Expected
Coverage
Butterfly Network, Inc. · Next earnings unconfirmed at scoring · Score 49 · Grade C
Embed this score
Copy the HTML below to show this score on your site. The badge links back to this page and updates automatically when the score changes.
Preview:
BlitzLab scores businesses against a scholar’s standard — not investment advice. No price targets, no buy/sell recommendations. Figures are from SEC filings (XBRL) as labeled in the source scorecard.