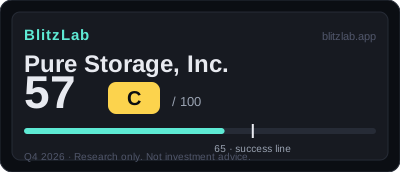
Pure Storage, Inc. — Blitz Index 57 (C)
Pure Storage scores 57 — all-flash storage growing 38% with a ~70% gross margin and no debt, held back by stock-based compensation that recycles 99.6% of free cash flow.
Last re-scored: August 26, 2026.
Confidence: High · Category: ai-infra
Score breakdown
| Section | Score | Detail |
|---|---|---|
| A · Speed | 19 / 25 | Growth re-accelerating: FY2026 +16% → Q2 FY2027 +38%, products +54%, RPO +40%, guidance raised to $5.03–5.07B — hyperscale and AI storage are the second engine |
| B · Moat | 32 / 60 | Evergreen lock-in plus a ~70% margin plus $2.2B of deferred revenue — a solid moat, though the market (B3 8) and distribution (B2 8) are enterprise, not viral |
| C · Creative destruction | 9 / 15 | All-flash displacing disk is in its mature phase — the displacement is real but no longer new, and the next test is how large hyperscale becomes |
| D · BlitzFailing | −3 | Deductions of only 3: no debt (D1 0); the SBC leak — $482M of stock compensation against $616M of FCF (D2 −2); supply commitments of ~$1.1B (D4 −1) |
Think we scored it wrong? Score it yourself →
Radar axes (0–100): Moat 53.3 · Speed 76.0 · Creative 60.0.
Watch item
Gates: G1 ✓ (confirmed — growth sustained and re-accelerating: Q2 FY2027 +38%, products +54%, plus a second engine in hyperscale and AI storage) · G2 ✓ (estimated — the AI storage and all-flash markets clear the bar). 8 points below the 65-point threshold — first score. No FLAG: deductions of only 3. Watch: whether the SBC ratio falls, whether hyperscale becomes a durable axis rather than a quarter's spike, and whether the thin 5.3% GAAP operating margin widens. Note: ARK's CSV lists this holding as Everpure Inc.; the operating business is Pure Storage (renamed 2026-02-23, ticker PSTG → P).
Strengths
- Growth re-accelerating: Q2 +38% YoY, products +54%, ARR +20%, RPO +40%
- Second axis: hyperscale and AI storage, overseas +75% YoY (42% of revenue)
- High margins: GAAP gross margin of 68.4%, non-GAAP 69.9%, FY2026 ~70.4%
- Net cash: borrowings of $0, cash and securities of ~$1.5B, free cash flow of $616M
- Visibility: deferred revenue of $2.2B, RPO of $3.7B, guidance raised
Concerns
- SBC leak: $482M of stock-based compensation is 4.19× operating profit, and buybacks plus withholding of $614M recycle 99.6% of free cash flow
- Thin GAAP operating margin: 5.3% — the margin converts to profit slowly
- Supply commitments: ~$1.1B of component commitments, Q2 operating cash outflow of −$136M
- Maturing displacement: all-flash substitution is in its later phase (C 60.0)
- Headcount, direct share and proxy unconfirmed — the limits on A3, A4 and D3 precision
Research notes
Thesis: re-accelerating growth, with the cash leaking out through stock comp
Pure Storage enters the BlitzLab record with a first scoring of 57 out of 100, grade C, built from Speed 19 out of 25, Moat 32 out of 60, Creative Destruction 9 out of 15, and deductions of 3. The total sits 8 points below the 65-point line, and the shape of the score is the story: speed converts to 76.0 and the moat to 53.3, while creative destruction converts to 60.0. This is the all-flash storage company — trailing-twelve-month revenue of about $4,262 million — whose growth re-accelerated from 16% in fiscal 2026 to 38% in the second quarter of fiscal 2027, with products up 54% and remaining performance obligations up 40%, on hyperscale and AI storage as the second engine. The gross margin is about 70% and there is no debt. The leak is stock-based compensation: $482 million of it, 4.19 times operating profit, with buybacks and withholding of $614 million recycling 99.6% of the $616 million of free cash flow. ARK's CSV lists this holding as Everpure Inc.; the operating business is Pure Storage, renamed on 2026-02-23 with the ticker changed from PSTG to P.
The gates: both pass — the next test is hyperscale's durability
Gate 1, sustained growth or a second growth curve for a mature company, passes on a confirmed basis. Revenue growth re-accelerated to 38% in the quarter, products grew 54%, annual recurring revenue grew 20%, and the second engine — hyperscale and AI storage, with overseas revenue up 75% — is visible in the order book. Gate 2, a ten-year market ceiling at least ten times current revenue, passes as an estimate on the AI storage and all-flash markets. The fourth quarter of 2026 has not been reported at T, and its reporting date is unconfirmed — it is not a company-confirmed date and must not be presented as one — and no outcome is anticipated here. That is the balance of the record at T: a high-margin, debt-free storage business growing 38%, whose margin barely reaches shareholders after stock compensation, and whose next test is whether hyperscale is a durable axis or a quarter's spike.
The business: all-flash storage, now selling to hyperscalers
The listed company is Everpure Inc., ticker P, and the operating business is Pure Storage: renamed on 23 February 2026, with the ticker changed from PSTG to P. It sells all-flash storage — FlashArray and FlashBlade hardware, the Purity software that runs it, the Evergreen subscription that turns storage into a service, and the Portworx container platform. Growth has re-accelerated: total revenue rose 38% year on year in the second quarter of fiscal 2027, after 16% for fiscal 2026 as a whole, with product revenue up 54% and remaining performance obligations at $3.7 billion, up 40% year on year. The second engine is hyperscale and AI storage: overseas revenue rose 75% year on year to 42% of total revenue, a record share. Trailing revenue is about $4,262 million.
Why it scored 57: re-acceleration on top, a leak underneath
Speed scores 19 of 25, led by growth (A1, 8 of 10): fiscal 2026 at 16%, the first quarter of fiscal 2027 at about 28% on guidance, the second quarter at 38%, with products up 54% and remaining performance obligations up 40%. The two points not awarded are for what the 38% contains — large-deal timing from hyperscalers, and a low fiscal 2026 base. Capital speed (A2, 4 of 5) is self-generated: fiscal 2026 operating cash flow of $880 million and free cash flow of $616 million at a 16.8% margin, with the $125 million acquisition of 1touch and $343 million of buybacks absorbed without external funding. Hiring (A3, 3 of 5) cannot be verified: the headcount is undisclosed. Share speed (A4, 4 of 5) is visible in the numbers that stand in for share — overseas revenue up 75% and remaining performance obligations up 40% — but no direct share figure is disclosed.
The moat scores 32 of 60. Network effects (B1, 7 of 18) are switching-cost and ecosystem effects rather than platform lock: Purity software and the Evergreen subscription are embedded in the installed base, data migration costs make switching expensive, and the Portworx container ecosystem widens the ecosystem. Distribution (B2, 8 of 18) repeats and expands: direct sales, channel partners and hyperscaler original-equipment deals, Evergreen//One storage-as-a-service, and remaining performance obligations of $3.7 billion, up 40%. Market size (B3, 8 of 12) is large in the broad definition and small in the narrow one: the broad data-storage market exceeds $200 billion by 2030, against which trailing revenue of $4.26 billion is about 2%, but hardware alone is about $35 billion a year, below the bar of $42.6 billion. Gross margin (B4, 9 of 12) is high and stable — a GAAP gross margin of 68.4% in the second quarter of fiscal 2027, about 70.4% for fiscal 2026 — but stock-based compensation of $481.7 million is 4.19 times operating profit.
Creative destruction scores 9 of 15, three even items that describe a transition in its later stages. What is being displaced (C1, 3 of 5) is clear: all-flash replacing hard-disk drives and disk arrays, a conversion Pure led and that has now been running for more than ten years, so its novelty is low; AI storage is the second replacement axis and it is still early. The behaviour change (C2, 3 of 5) is hard to reverse — once a customer is inside Evergreen//One or Evergreen//Forever, there is no reason to return to capital-expenditure refresh cycles — but the change belongs to the industry's as-a-service shift as a whole rather than to Pure. The cost-structure change (C3, 3 of 5) is real at the unit level — cost per terabyte, power and space are structurally lower than disk.
The risks: three points of deductions — and the leak is stock compensation
The deductions total 3, far below the 15-point FLAG line, but one of them is structural. Debt (D1, 0) is a non-issue: borrowings are zero, a $500 million revolver is unused, cash and securities are about $1.5 billion, and net cash is about $0.64 billion. Revenue quality (D2, minus 2) is the leak: fiscal 2026 stock-based compensation of $481.7 million is 4.19 times operating profit and 78% of free cash flow of $615.7 million, and buybacks of $342.6 million plus withholding of $270.9 million recycle 99.6% of free cash flow, leaving $2.2 million of residual cash for shareholders. Governance (D3, 0) carries no disclosed dual-class structure or founder control in the record, with the proxy not yet checked. Regulation (D4, minus 1) reflects component supply commitments of about $1.1 billion through 2027, about 26% of revenue.
What would change the score
Pure Storage is eight points below the 65 line, and the two questions that decide the next move are durability and leakage. The first is whether hyperscale is a durable axis or one quarter's spike: the 38% growth and the 40% rise in remaining performance obligations need to repeat, and delivery of the raised fiscal 2027 guidance of $5.03–5.07 billion is the test. The second is the stock-compensation leak: if the ratio of stock-based compensation to operating profit and free cash flow falls, the 70% gross margin starts to mean something for shareholders, and the minus 2 on revenue quality can narrow. The supply commitments of about $1.1 billion need to clear without a demand slowdown turning them into inventory.
More AI Infra companies
Other AI Infra names on the Blitz Index, highest score first: NVIDIA (87/A), Arista Networks (73/B), Advanced Micro Devices (62/B).
Next earnings
Nov 18, 2026 · After close · Confirmed
Coverage
Pure Storage, Inc. · Next earnings unconfirmed at scoring · Score 57 · Grade C
Embed this score
Copy the HTML below to show this score on your site. The badge links back to this page and updates automatically when the score changes.
Preview:
BlitzLab scores businesses against a scholar’s standard — not investment advice. No price targets, no buy/sell recommendations. Figures are from SEC filings (XBRL) as labeled in the source scorecard.